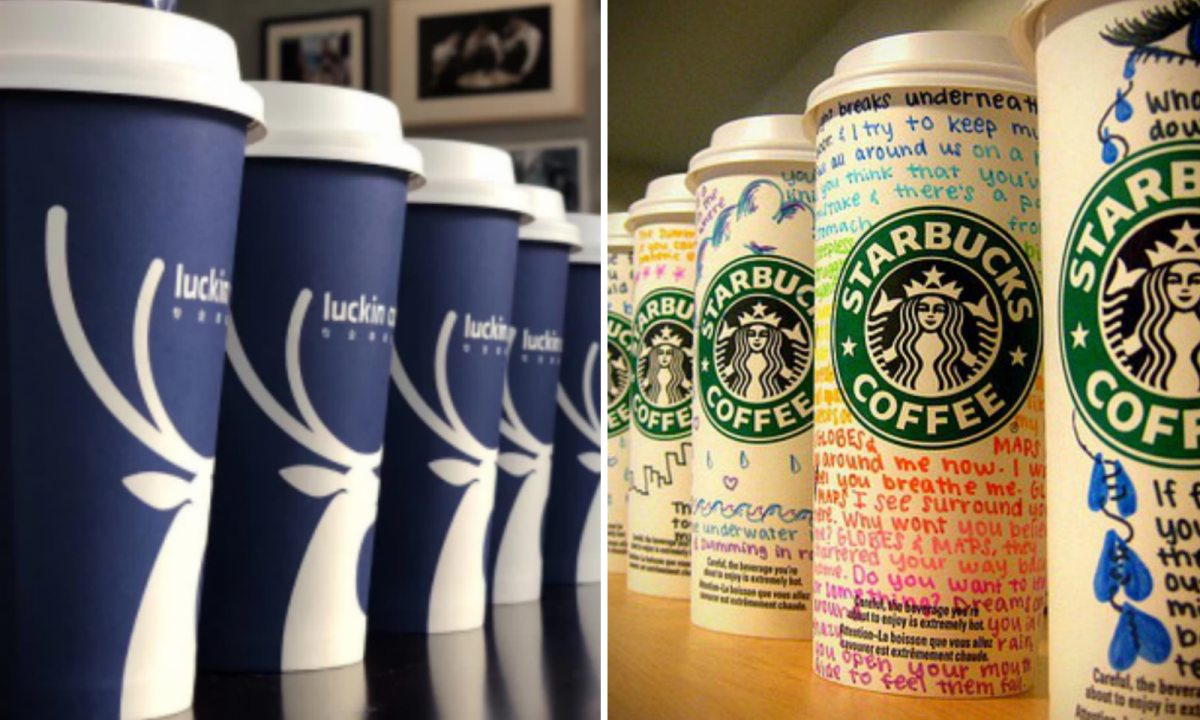
Luckin Coffee vs Starbucks battle in China: How wins?
By the end of 2024, Luckin Coffee had over 20,000 stores in China, compared to approximately 7,500 Starbucks locations. In 2022, Luckin passed Starbucks at 7,100 stores versus 5,400. Since then, Luckin has never looked back. The company’s net income rose 72.4% in Q2 2022, and its raw coconut latte sold 100 million cups within a year of launch. The accounting scandal that nearly destroyed the company in 2020 is now primarily a business school case study. In China’s daily reality, Luckin is the dominant coffee brand. What Luckin did right tells you a great deal about how to build a consumer brand in China in 2026.
How Luckin Won China’s Coffee War
Luckin’s recovery and growth came from three decisions that proved consistently correct in the Chinese market.
First: product innovation at high speed. Luckin launches new drinks constantly. Not all succeed, but when one does, it becomes a cultural phenomenon. The raw coconut latte (生椰拿铁) launched in April 2021 and sold 10 million cups in its first month. By April 2022, on its one-year anniversary, it had sold 100 million cups. The sauce latte (酱香拿铁), a collaboration with Moutai baijiu, sold 5.42 million cups on its first day in September 2023. Luckin treats its drinks menu as a product development engine, not a static menu. New flavor drops function like brand campaigns: they generate social media content, press coverage, and foot traffic simultaneously.
Second: mobile-first ordering and accessibility at scale. Luckin’s entire model is built around the app. No queuing, customization options that Starbucks cannot match on volume, delivery integration, and a loyalty program that keeps users in the Luckin ecosystem between purchases. This mobile-native approach has proven more aligned with how young Chinese consumers want to buy coffee than Starbucks’ cafe experience model.
Third: aggressive lower-tier city expansion. Luckin expanded rapidly into second and third-tier cities where Starbucks had fewer locations. This strategy captured the rising coffee culture outside China’s first-tier cities before competitors could establish a foothold. 87% of Tongcheng Travel’s users come from non-first-tier cities. The same demographic breadth is reflected in Luckin’s customer base.
The Chinese Coffee Market in 2026
China’s coffee culture is no longer emerging. It has emerged. Approximately 600 million Chinese consumers drink coffee with some regularity, according to industry data discussed widely in Chinese retail and consumer research media. The market is competitive at every price tier:
- Luckin Coffee: 20,000+ stores, dominant in mobile-first ordering, product innovation, tier 2-3 city expansion.
- Starbucks China: 7,500+ stores, premium positioning, café experience model, loyalty program with 22M+ members.
- COTTI Coffee: Founded by Luckin’s original founders after their departure. Aggressive pricing and expansion, targeting price-sensitive consumers with 9.9 RMB drinks.
- Manner Coffee: Premium boutique positioning, smaller footprint, strong appeal among young Shanghai and Beijing professionals who want quality without Starbucks pricing.
- M Stand: Design-forward positioning, high Xiaohongshu engagement, a destination rather than a convenience stop.
Luckin vs Starbucks China: Key Numbers
| Brand | Store Count | Positioning | Key Platform |
|---|---|---|---|
| Luckin Coffee | 20,000+ (end 2024) | Mobile-first, accessible, innovation-driven | Luckin app, Douyin, WeChat |
| Starbucks China | ~7,500 | Premium café experience, brand status | Starbucks app, WeChat, Xiaohongshu |
| COTTI Coffee | Growing rapidly | Ultra-low price point (9.9 RMB) | Douyin, delivery platforms |
| Manner Coffee | Several hundred | Quality boutique, young professional | Xiaohongshu |
| Luckin raw coconut latte | 100M cups in first year | Viral product launch model | Xiaohongshu, Douyin, WeChat |
What Any Consumer Brand in China Can Learn From Luckin
The Luckin story is not just a coffee story. It is a master class in Chinese consumer brand building. Three lessons apply broadly:
Product drops as marketing campaigns. Each new Luckin drink launch is a media event. The brand does not announce products through advertising. It creates products worth talking about and lets Chinese social media do the work. The Moutai collaboration generated national press coverage the day it launched without a single paid media placement. If a product is interesting enough, Chinese consumers will generate the content for you.
Price points that create habit, not occasion. Luckin’s 9.9-15 RMB drinks make coffee a daily habit rather than a special occasion. This frequency of purchase builds brand attachment that premium-priced competitors struggle to match. The occasional Starbucks buyer has a different relationship with the brand than the twice-daily Luckin customer.
App and private domain ownership. Luckin’s app is not just an ordering tool. It is a customer relationship management system that gives the brand direct access to its consumers without depending on third-party platforms. This private domain, combined with gamified loyalty mechanics, generates repeat purchase rates that industry analysts consistently note as among the highest in China’s food and beverage sector.
How to Reach Chinese Coffee Consumers on Xiaohongshu (RedNote)
1. Product-first content, always. Chinese coffee consumers on Xiaohongshu share drink discoveries. A new flavor, an unusual combination, a limited-edition seasonal cup, or a barista’s signature creation gets posted immediately. Brands and cafes that create genuinely interesting drinks generate organic Xiaohongshu content at no cost.
2. Cafe aesthetics drive discovery. Chinese consumers on Xiaohongshu actively seek photogenic cafes. Interior design, cups, art, and the overall visual experience of a cafe are as important as the coffee quality for generating discovery posts. M Stand and Manner both benefit from strong Xiaohongshu aesthetic identity that generates tens of thousands of organic posts from visitors.
3. Coffee knowledge content builds brand authority. Chinese coffee culture is maturing rapidly. Consumers in major cities now distinguish between brewing methods, origin regions, and processing styles. Xiaohongshu content that genuinely educates about coffee quality, sourcing, or preparation builds brand authority for premium operators that price and flavor alone cannot establish.
How to Reach Chinese Coffee Consumers on Douyin
4. Collaboration product launches generate Douyin content at scale. Luckin’s Moutai collaboration was a Douyin phenomenon. The product concept was interesting enough that Chinese users created review and reaction content organically. Any coffee brand creating genuinely novel collaborations, whether with alcohol brands, cultural institutions, or seasonal ingredients, can benefit from this same dynamic.
5. Live commerce drives repeat purchases. Luckin sells heavily through promotions on its own app, but other coffee brands and premium operators can use Douyin live commerce to push gift cards, brand merchandise, and seasonal products. Live commerce integrates coffee culture content with direct purchase in a format that Chinese consumers respond to.
Example Found on Chinese Web (Translated)
“Luckin’s sauce latte was everywhere on my Douyin the day it launched. I had to try it. I queued 40 minutes. It’s not even my favorite coffee. But I had to try the thing everyone was talking about. That’s exactly what they wanted me to do. I respect it. I’ll do it again next time they launch something ridiculous.”
— Xiaohongshu post from a Hangzhou professional, September 2023, on the day of the Luckin x Moutai sauce latte launch
FAQ
Has Luckin Coffee beaten Starbucks in China?
By store count, yes and by a large margin: 20,000+ Luckin versus 7,500 Starbucks by end 2024. By revenue, the two compete closely at the top tier. By consumer volume and daily purchase frequency, Luckin is the clear leader. Starbucks retains a strong premium and aspirational positioning among specific consumer segments.
What made Luckin’s raw coconut latte so successful in China?
The product hit a flavor profile that appealed to Chinese consumers (coconut is widely popular), launched with effective social media seeding on Douyin and Xiaohongshu, was priced accessibly, and benefited from the scarcity mechanics of a new product release. The combination of genuine palatability and social media buzz created a self-reinforcing sales cycle.
How big is China’s coffee market in 2026?
Approximately 600 million Chinese consumers drink coffee with some regularity. The market has grown consistently at double digits annually since 2018. China is now one of the world’s most competitive and dynamic coffee markets, with innovation from both domestic and international brands setting global trends in product development and distribution models.
What is COTTI Coffee?
COTTI was founded by Luckin’s original co-founders after departing the company. It uses ultra-low pricing (9.9 RMB or lower for many drinks) and aggressive expansion to compete at the accessible end of the market. It represents a direct competitive challenge to Luckin’s position with budget-conscious consumers in tier 2-4 cities.
We track China’s consumer brand landscape including food, beverage, and retail trends on our LinkedIn page. Follow us for regular updates on China’s most important consumer categories.
The Luckin Model Is a Blueprint. Let Us Apply It to Your Brand in China.
Product innovation as social media content. Mobile-first purchasing. Aggressive tier 2-3 city expansion. App-driven private domain. These are not coffee industry tactics. They are Chinese consumer brand tactics that work across categories. We help international and domestic brands apply this kind of systematic, platform-integrated consumer strategy to their China market entry or growth plans. If you want to build a consumer brand in China that drives real purchase frequency, not just awareness, let us show you what that looks like for your category.
Contact us to discuss your consumer brand strategy for China.

Pedro Wang is the founder of Chinese Tourists Agency, based in Shanghai. He spent ten years in the Chinese travel industry at CITS and Ctrip before opening the agency. More about Pedro and the team here.